Managing food production expenses is essential for restaurants that prepare meals in-house, run bakeries, or produce food through central kitchens.
Understanding the Cost of Goods Manufactured(COGM) helps restaurant owners to calculate the expenses of products completed during a certain period. While ingredients, kitchen labor, equipment expenses, and food waste can all affect production expenses and overall profits.
The Cost of Goods Manufactured formula considers direct materials, direct labor, manufacturing overhead, and changes in work-in-process inventory.
Calculating these components correctly helps restaurant managers evaluate production costs, improve purchasing decisions, and find opportunities to reduce food waste.
It also helps them to understand the difference between COGM and Cost of Goods Sold(COGS), which measures the cost assigned to products sold during a period.
Understanding how to calculate COGM can support better menu costing, budgeting, inventory management, and production planning. Restaurant owners can also use restaurant data analytics solutions to examine cost trends and identify unusual changes in operational performance.
Platforms like Livelytics offer restaurant analytics solutions that businesses can explore to gain operational insights. Based on available integrations and configuration, Livelytics may help to analyze valid restaurant data and support informed decisions.
This guide explains the COGM formula, step-by-step calculations, common mistakes, and practical strategies for managing production costs more effectively.
Also Read: Restaurant Profit Margin Analytics Tools to Boost Profit
Breaking Down of Cost of Goods Manufactured
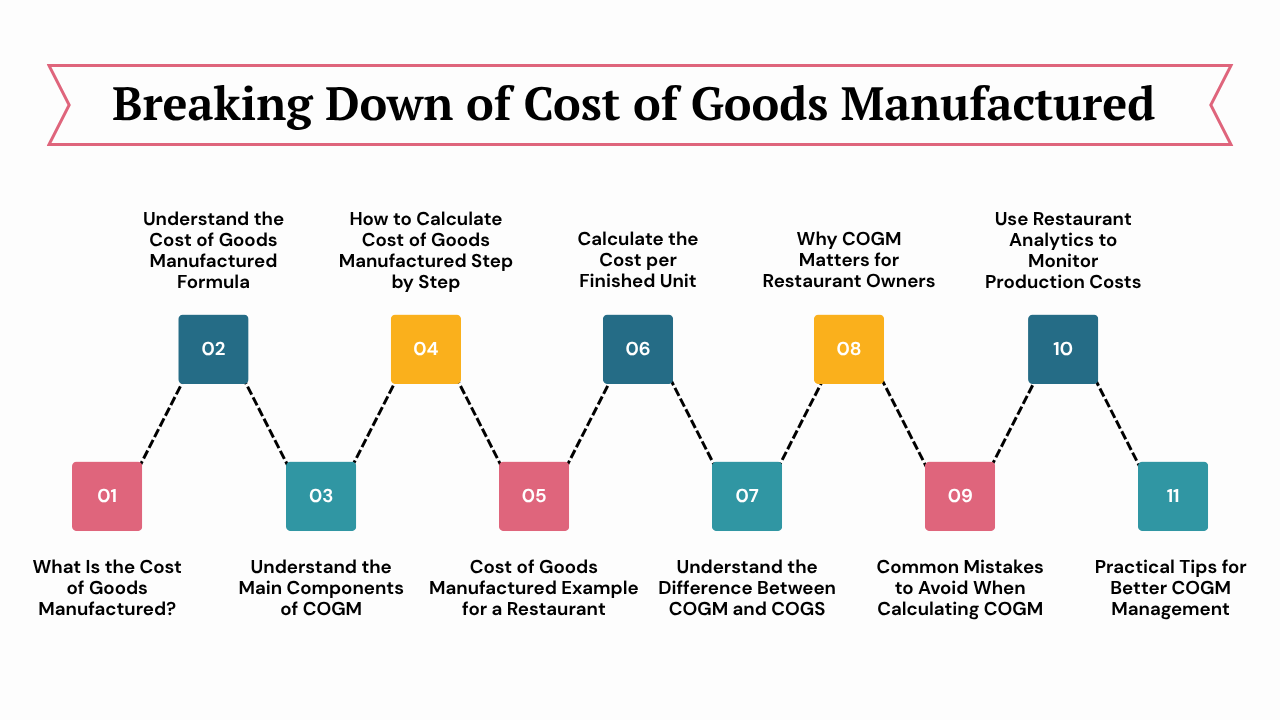
1. What Is the Cost of Goods Manufactured?
Cost of Goods Manufactured(COGM) is the total cost assigned to products completed during a specific accounting period. It includes the materials used, labor involved in production, and applicable production expenses, adjusted for beginning and ending work-in-progress inventory.
For instance, a restaurant may prepare sauces, baked goods, or packaged meals in advance. By calculating production expenses can help restaurant managers to understand how much it costs to manufacture those items before they are sold or transferred to another location.
However, COGM is not the standard measurement for every restaurant. A conventional restaurant that purchases ingredients and prepares dishes directly for customers will often find Cost of Goods Sold(COGS) and food-cost percentage more directly useful.
Such distinction matters because COGM measures the costs of completed production, whereas COGS measures the cost assigned to products sold or consumed during that duration.
Also Read: The Blind Spots Costing Your Business More than you think
2. Understand the Cost of Goods Manufactured Formula
This formula calculates production expenses and then adjusts them for unfinished work.
Cost of Goods Manufactured = Total Manufacturing Costs + Beginning Work-in-Process Inventory − Ending Work-in-Process Inventory
Total manufacturing costs consist of three main components:
Total Manufacturing Costs = Direct Materials Used + Direct Labor + Manufacturing Overhead
Combining these equations gives the complete formula:
COGM = Direct Materials Used + Direct Labor + Manufacturing Overhead + Beginning WIP − Ending WIP
WIP represents work-in-process inventory which represents products that have started production but are not yet completed.
For a restaurant producing packaged meals, beginning WIP inventory includes costs assigned to partially prepared meals from the previous period while ending WIP inventory shows the production expenses of meals that are still incomplete at the end of the current period.
Here, beginning WIP is added because it includes costs from earlier work that may be completed during the current period. While ending WIP is subtracted because those products are not yet finished. Such calculation helps to find the cost of products completed during the period without considering all current production spending as completed output.
Also Read: Cost Effective AI Solutions for Restaurants
3. Understand the Main Components of COGM
Accurate COGM calculations require restaurant owners to identify and classify costs consistently.
Direct Materials Used
Direct materials include the ingredients and supplies that can be directly identified with the preparation of specific food products. For a bakery, these materials include flour, sugar, butter, eggs, and chocolate.
For a central kitchen, direct materials used can include rice, vegetables, meat, sauces, and meal packaging because packaging is part of the production cost of products.
Direct materials used are not necessarily equal to the value of ingredients purchased during that period. Some purchases remain in storage, while ingredients available at the beginning of the period may be consumed during production.
A basic calculation is:
Direct Materials Used = Beginning Raw Materials + Purchases − Ending Raw Materials
It is essential to make adjustments that may be necessary for purchase returns, discounts, freight-in, and indirect materials, based on the accounting method. Ingredients that cannot be traced directly to specific products may need to be classified as indirect materials.
Direct Labor
Direct labor includes the labor costs directly attributable to preparing or producing the finished products.
For a central kitchen, these expenses include the income of staff who prepare, assemble, bake, or pack products. It may also include employer payroll taxes and employee benefits when the accounting policy considers them as production labor expenses.
Restaurant owners should differentiate production labor from other labor expenses. General admin, marketing, and front house activities do not instantly come under direct production labor. Consistently tracking these expenses and clear staff responsibilities make this calculation more reliable.
Manufacturing Overhead
Manufacturing overhead is the indirect production expenses that cannot be traced conveniently to a specific product but are associated with the production operation.
For a restaurant production kitchen, potentially valid expenses include kitchen equipment depreciation, production-area utilities, maintenance, indirect kitchen labor, and other production expenses.
While rent, utilities, cleaning supplies, equipment expenses, and similar expenses are based on the way it is related to production and the applicable accounting policy. Any costs should not be included only because they occur inside a restaurant.
Restaurants must not automatically include selling expenses, marketing, general admin, and other period expenses should not automatically be included in COGM.
Beginning and Ending Work-in-Process Inventory
Beginning WIP is the production expenses assigned to unfinished products at the beginning of the accounting period. Ending Work-in-process is the corresponding cost of products still finished at the end.
For instance, a catering company may start a month with partially assembled meal orders and finish them during that month. The cost carried forward from those unfinished orders forms part of beginning work-in-process.
At month-end, partially prepared meals may remain under the end of the Work-in-process. Such expenses must be estimated consistently as per the stage of completion.
Restaurants that prepare food for immediate service may have little or no material WIP at the reporting cutoff. In those cases, the WIP adjustment may be unnecessary or relatively small.
Also Read: How to Fix Store to Store Performance Gaps With Data
4. How to Calculate Cost of Goods Manufactured Step by Step
Restaurants must follow these steps while calculating cost of goods manufactured(COGM) for a restaurant’s production kitchen, bakery.
Step 1: Identify the accounting period
Choose a consistent period, like a month or quarter. It involves gathering inventory records, purchase invoices, payroll records, production reports, and applicable overhead information for that duration.
Step 2: Calculate direct materials used
Start by calculating beginning raw materials inventory, add eligible purchases, and subtract ending raw materials inventory. While adjustments must be made for returns, discounts, freight-in, or indirect materials when applicable.
Step 3: Calculate direct labor
Identify the labor expenses that are directly attributed to the products completed. They must use reliable payroll records and production time records to avoid including unwanted labor costs.
Step 4: Calculate manufacturing overhead
Collect qualifying indirect production costs. If overhead is allocated using a rate, then they must document the chosen allocation basis and apply it consistently.
Step 5: Calculate total manufacturing costs
Calculate total manufacturing expenses by adding direct materials used, direct labor, and manufacturing expenses.
Step 6: Adjust for WIP inventory
Include the beginning work-in-progress(WIP)inventory in the calculation and subtract the ending work-in-progress inventory to find the cost of completed products.
Step 7: Review the result
Restaurants must check the calculation against production quantities, inventory records, and financial reports. They must evaluate unusual changes before using the result for pricing or profit decisions.
Following a consistent process makes it easier for restaurants to compare production expenses between accounting periods.
Also Read: Restaurant Profit Margin Analytics Tool to Boost Profits
5. Cost of Goods Manufactured Example for a Restaurant
Assume a restaurant group that prepares packaged meals in a central kitchen and distributes meals to its branches. During a month, the kitchen records $8000 in beginning raw materials inventory, purchases $25000 in additional materials, and has $6000 in ending raw materials inventory.
Using these figures lets the restaurants calculate direct materials used by adding beginning inventory to purchases and subtracting ending inventory. The result is $27,000 in direct materials used.
Next, the restaurant adds $9000 in direct production labor and $4,000 in manufacturing expenses which brings total manufacturing expenses to $40,000.
To determine the Cost of Goods Manufactured (COGM), the kitchen adds $2,000 in beginning work-in-process (WIP) inventory and subtracts $3,000 in ending WIP inventory. Therefore, the final COGM is $39,000 for the month.
This calculation assumes there are no purchase returns, indirect-material adjustments, or other relevant raw materials adjustments. The $39,000 represents the production cost assigned to products completed during the period.
However, it does not necessarily equal the cost of products sold because some completed meals may remain in finished inventory, while others sold during the month may have been produced earlier.
Also Read: How Does Data Analytics Help Restaurants Grow
6. Calculate the Cost per Finished Unit
Calculating the total cost of goods manufactured(COGM)helps restaurant owners to understand overall production expenses. However, finding the cost of each finished unit gives additional insight into the resources needed to produce individual meals. Such information can enable menu costing, pricing decisions, and production planning.
The formula for calculating with the cost per finished unit is:
Cost per Unit = Cost of Goods Manufactured ÷ Units Completed
For instance, assume a restaurant’s central kitchen records a COGM of $39000 and completes 3,000 packaged meals during the month. Dividing the total production expenses by the number of completed meals gives an average cost of $13 per finished meal.
Calculating this average is most useful when the meals have the same ingredients, food portion sizes, and production requirements. If the kitchen prepares different products, like vegetarian meals, chicken dishes, desserts, and premium catering options, calculating expenses separately for each product or back can give more accurate results.
Understanding the cost per unit helps restaurant managers to compare production costs, identify rising expenses, and evaluate if current menu prices support business goals.
However, the production expenses alone does determine the final selling price. Rather restaurant owners should also consider operating expenses, customer demand, competitor pricing, and desired profit margins before setting prices.
Also Read: The Blind Spots Costing Your Business More than You Think
7. Understand the Difference Between COGM and COGS
It is essential for restaurants to understand the difference between Cost of Goods Manufactured(COGM) and Cost of Goods Sold(COGS). It helps restaurant owners to track product costs and the cost of products sold.
Although both these metrics are interconnected, they measure different phases of the inventory process. COGM indicates the production costs assigned to goods completed during an accounting period. Whereas COGS indicates the cost assigned to goods sold during that period.
For products that are tracked through finished-goods inventory, COGS is calculated by adding finished-goods inventory to Cost of Goods Manufactured(COGM) and subtracting ending finished-goods inventory.
For instance, if beginning inventory is $5000, Cost of Goods manufactured is $39000, and ending inventory is $7000, then the resulting Cost of Goods sold is $37000.
Traditional restaurants usually calculate ingredient-based COGS using beginning inventory purchases, and ending inventory. Additional adjustments are also applicable based on inventory transfers, returns, food waste, and accounting procedures. Restaurants can also calculate food-cost percentage by dividing COGS by food sales and multiplying the result by 100.
When restaurants keep COGM and COGS separate, it helps restaurant managers to distinguish production expenses from sales-related inventory expenses. This information supports more accurate financial reporting, inventory management, cost monitoring, and business planning.
Also Read: Customer Sentiment Analysis Vs Traditional Surveys
8. Why COGM Matters for Restaurant Owners
Calculating cost of goods manufactured(COGM) helps restaurant owners to understand production costs and make better operational decisions. Although not every restaurant requires a formal COGM statement, it can be specifically valuable for businesses that prepare food in batches, run multiple kitchens, or produce packaged meals for distribution.
- Improve cost visibility: It helps to separate materials, labor, and expenses that help restaurant managers to identify the biggest contributors to production expenses.
- Support pricing decisions: Accurate cost information helps restaurant owners to check whether product prices cover production expenses and cause operating expenses.
- Monitor production efficiency: Comparing expenses across periods can reveal changes in ingredient usage, labor requirements, and allocation of overhead.
- Reduce waste: Any unexpected differences in materials use may indicate food spoilage, overproduction, food portioning inconsistencies, or inventory recording mistakes.
- Improve inventory planning: Monitoring raw materials, unfinished products, and completed goods supports effective material purchasing, and production schedules.
- Support budgeting: Past COGM figures help managers to predict production expenses and compare actual expenses with planned budgets.
For gaining impactful insights, restaurant owners require accurate inventory records and consistent cost classifications. COGM should also be reviewed along with sales, labor, and waste information.
Considering all these measures together provide a clearer understanding of operational performance and helps restaurant managers to identify opportunities to control expenses and improve efficiency.
Also Read: How Restaurant Owners Can Use Data to Make Better Decisions
9. Common Mistakes to Avoid When Calculating COGM
Small errors in inventory records or cost classification can make COGM misleading. Restaurant owners should watch for the following problems.
Counting purchases as materials used: Ingredients purchased during the month may remain in storage. Restaurants must adjust purchases for beginning and ending raw materials inventory rather than assuming that every purchased material was used.
Mixing direct and indirect costs: Materials and labor that cannot be included directly to products may require to be included in overhead instead of counting it twice.
Ignoring WIP inventory: When unfinished production is material, excluding beginning or ending work-in-process can distort the expenses of completed products.
Including unrelated operating expenses: Marketing, administrative costs, and other nonproduction expenses should not be automatically included in cost of goods manufactured.
Using inconsistent accounting periods: Ensure that inventory balances, purchases, labor expenses, and overhead costs are recorded consistently within the same reporting period for correct COGM calculations.
Overlooking food waste: Any food spoilage, food preparation losses can affect material usage. Restaurants must record and classify these items regularly rather than considering it as unexplained cost differences.
Using one average for very different products: Product-level or batch-level costing may be useful when ingredient requirements and food preparation times differ.
Consistent payment reconciliation and documented accounting policies make COGM calculations easier to review and compare.
Also Read: Why Do Restaurants Fail
10. Use Restaurant Analytics to Monitor Production Costs
Calculating COGM manually can help restaurant owners to know about production expenses, but regularly reviewing operational data makes it easier for restaurants to identify changes and analyze unusual patterns.
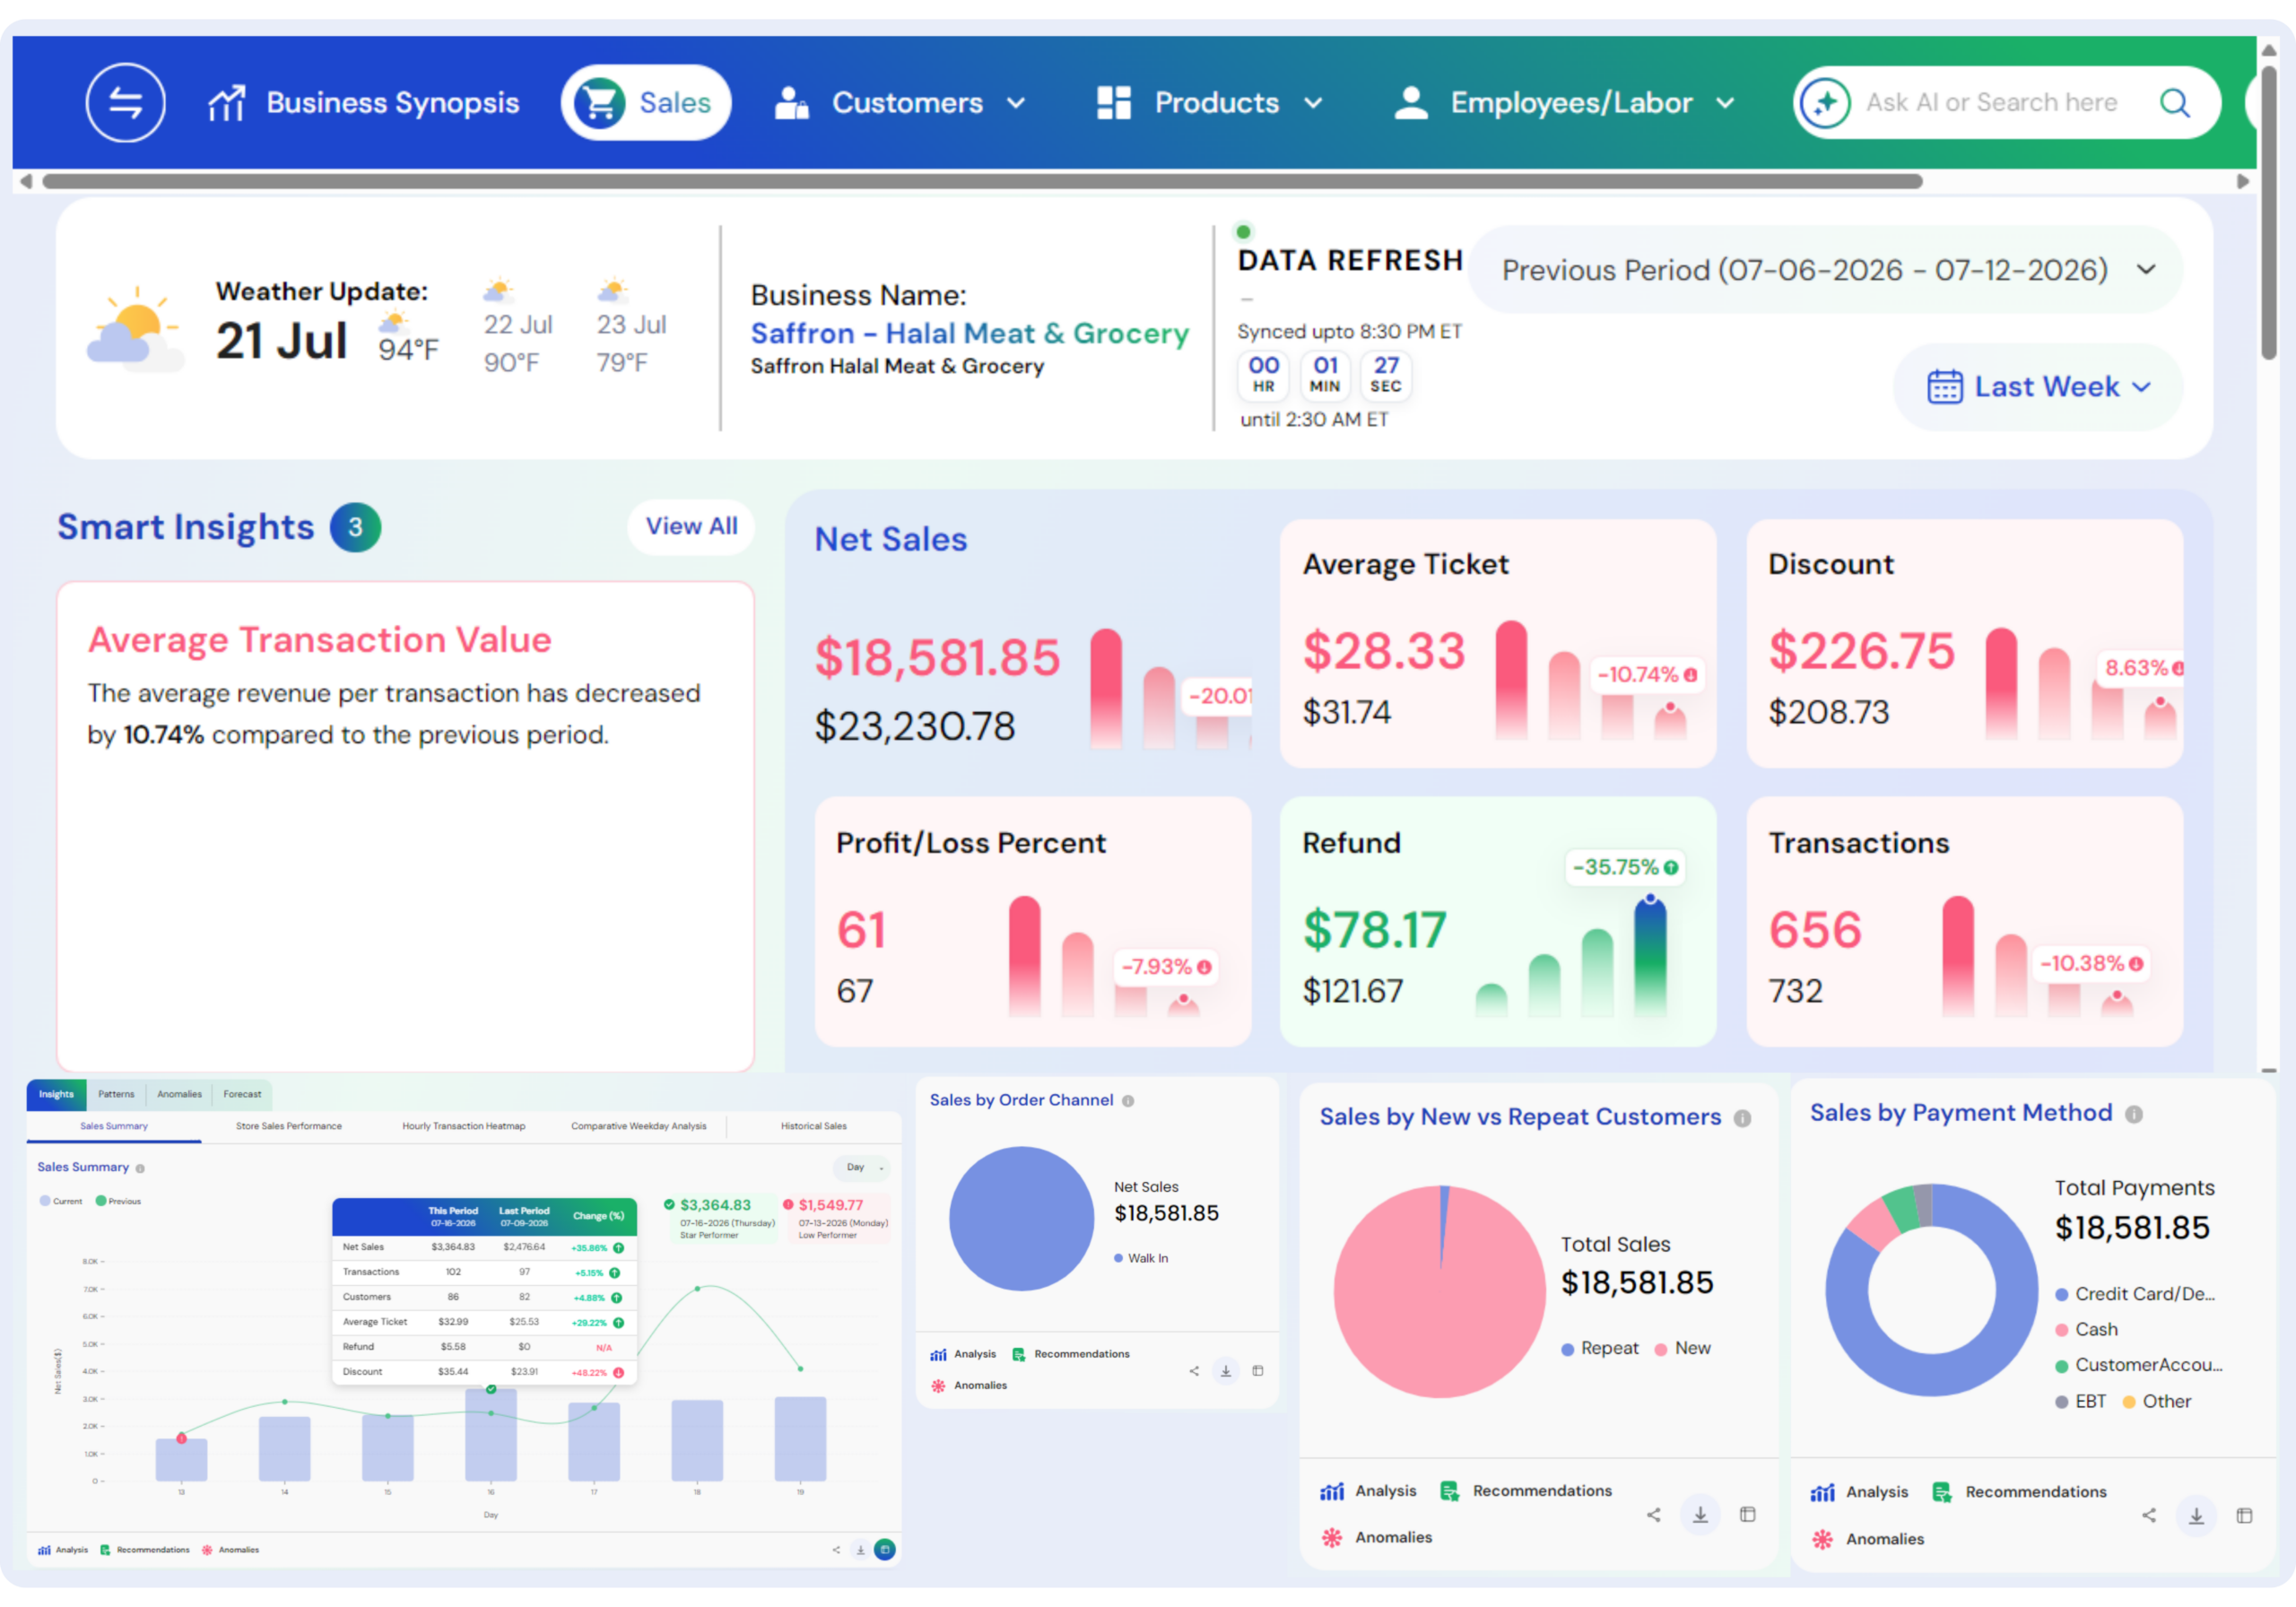
Restaurant analytics tools may help to integrate available sales, purchasing, inventory, and financial information. Based on integrations and configurations, such reports help restaurant managers to evaluate ingredient expenses, purchasing trends, food waste, and differences between expected and actual performance.
Livelytics offers restaurant analytics solutions that helps businesses to understand operational and performance insights. Based on the available data and system setup, analytics may help for production-cost reviews by helping restaurant managers to recognize patterns that need further analysis.
For example, if the cost of producing a batch of meals increases from one month to the next, a manager can review ingredient prices, production volumes, labor hours, waste records, and overhead allocations for understanding the change. This calculation helps to understand the difference and the data helps to explain possible causes.
Before choosing an analytics platform, it is essential for restaurants to check the systems that it supports, data it can access, and whether reporting capabilities are available in the chosen configuration.
Analytics cannot replace accurate stock counts, reliable payroll records or accounting practices. Rather, it helps restaurant managers to use these records more effectively and make better-informed operational decisions.
Also Read: How Restaurant Analytics and Reporting Drive Better Business Decisions
11. Practical Tips for Better COGM Management
Restaurant owners can improve the usefulness of COGM calculations by following a consistent approach to production expenses.
- Maintain accurate inventory records: They must record raw materials, unfinished products, and finished inventory where applicable that helps to maintain accurate inventory records.
- Standardize recipes: Restaurants must use consistent ingredient quantities and food portion sizes that make use of materials more predictable.
- Track production labor: They must track the time spent preparing specific batches or products when practical.
- Document overhead allocation: Choose an appropriate cost-allocation method and apply it consistently.
- Review waste regularly: They must record food spoilage, food preparation losses, and rejected batches to find recurring problems.
- Compare periods: They must analyze important changes in material, labor, and overhead expenses instead of assuming that they are caused by more food production.
- Use product-level costing when necessary: Separate calculations for products with substantially different ingredient and labor requirements.
- Reconcile financial records: Compare inventory movements and production reports with accounting records before finalizing results.
The right level of detail is based on the business. For instance, a small bakery may require a simple batch-costing spreadsheet, while a restaurant group with a central production kitchen may use more centralized inventory and accounting systems.